


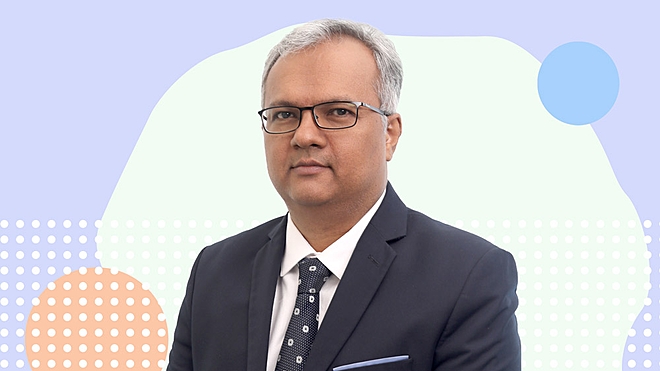

Though broader market indices continue to face significant declines, Rupesh Patel, Senior Fund Manager at Nippon Life India Asset Management, believes the market is yet to bottom out, as corrections have occurred only to a "certain extent". He also expects volatility to persist, primarily due to geopolitical factors. However, he remains optimistic about earnings growth and maintains that despite near-term volatility, India's medium- to long-term investment case remains "very much intact".
Patel currently manages two schemes at the fund house — the Nippon India Growth Fund and the Nippon India ELSS Tax Saver Fund — with total assets under management of Rs 43,630 crore. Of these, the Nippon India Growth Fund is rated four stars by Value Research.
In this interview, Patel discusses the factors that could drive a market rebound and whether valuations have turned attractive post-correction. He also shares insights into the strong performance of his growth fund and outlines the steps he plans to take to improve the performance of the Nippon India ELSS Tax Saver Fund.
Since September, we've seen a 13 per cent correction in the Sensex and even sharper falls in mid and small caps. Do you think the worst is over, or will volatility continue?
First, let's look at the correction in the mid- or small-cap indices. They have corrected by about 20-23 per cent from their September 2024 highs. They had compounded by around 35 per cent CAGR from the Covid-19 lows; small caps were even higher, at around 37 per cent. If we look at the Nifty index, it's down by 15 per cent after compounding at 24 per cent from March 2020. Having delivered such stellar returns for almost four years, we have seen a correction of around 14 per cent from the highs, and this drop should not surprise anybody. Now, the question arises: will this volatility persist or not? I sense it's challenging for somebody to categorically say that the market has bottomed out and the current volatility will go away. The volatility will continue, particularly driven by the global news flow.
Understanding the genesis of this correction is crucial. This correction was because of a mismatch between earnings growth expectations and the reality, which led to higher valuations. The situation appears to have been corrected to a certain extent. In summary, is the volatility expected to persist? My answer is yes, but from a medium- to longer-term perspective, the argument of remaining invested in India remains very much intact.
Weak earnings and sharp FPI outflows have weighed on the markets. What key factors could drive a recovery in the coming months?
As I said earlier if we look at this correction, the genesis of this correction was on account of the mismatch between the market's expectations and the reality of earnings growth.
Therefore, if I were to identify the most significant factor driving market returns, it would be a recovery in earnings growth. Today, when we look at the balance sheet of corporate India, it remains strong. Even the balance sheets of banks continue to be robust, with no worries on the NPA (non-performing assets) side. The fiscal and monetary policies remain favourable, and there are signs of improvement in rural consumption. Considering all these aspects, I believe the outlook for earnings growth should improve as we move ahead a few quarters. I believe this is one of the most crucial factors we need to monitor for markets to perform well in the future.
Will geopolitical factors continue to impact Indian markets?
There is no doubt that in the near term, if we look at the news flow, whether it is the talk around the US imposing tariffs on most of its trading partners or geo-global uncertainty emanating from various political decisions being taken globally, particularly in developed economies. I think it has led to risk premiums going up globally in markets, which is also reflected in the correction of valuations. India cannot be an exception in an environment like this, and for risk premiums to narrow and valuations to rise, some of these uncertainties must go away, so I think we'll have to learn to live with volatility, at least in the near term.
With the recent correction, are valuations looking more attractive now, or is caution still in certain pockets?
The kind of correction we have seen in most categories, whether large, mid or small cap, has come to their longer return averages or has gone slightly below the longer-term averages. However, I would not describe the market as extremely undervalued. Given
that the valuations are aligned with longer-term averages, the outlook for earnings growth is improving a few quarters down the line, and the cyclical and structural factors in India remain positive, I believe today's prices are significantly better than they were six months ago. Hence, I would say that today, the market is reasonably valued.
Could you share your core investment philosophy and how it adapts during uncertain market cycles?
Regarding investment philosophy, I would like to highlight a few points that have worked for me in my investing career. First, I tend to look at businesses with compounding characteristics run by decent management and efficient users of capital. Investors usually benefit if you buy such companies at the right valuation and hold them long enough for compounding to play out. So, I look at these kinds of businesses for the core part of my portfolio. I also believe for a patient investor, the market always provides opportunities in disliked sectors or stocks. These opportunities arise when there is a discrepancy between the market's perception of risk and reality. So those are other sets of opportunities that I look at. A combination of businesses with compounding characteristics and those disliked by the market because of some temporary disruptions, these two have the potential to generate significant returns.
The Nippon India Growth Fund has performed well over the past one and three years. What's worked in its favour?
The Nippon India Growth Fund is a mid-cap fund mandated to invest at least 65 per cent of the portfolio in mid-cap
stocks. But if I have to think of a few things that have worked for the fund, it would be our focus on bottom-up stock research or ideas. Our entire team backs this with solid research. Secondly, I would give credit to the diversification in the portfolio and participation in multiple profit pools. The third thing would be awareness about valuations.
Combining these things - picking up stocks on a bottom-up basis based on their fundamentals, keeping the portfolio diversified, trying to participate in as many profit pools as possible and being aware of valuations - has worked well for the fund. Moreover, our risk management framework, known as 'fund casing', has also played an essential role in risk management in this category.
The Nippon India ELSS Tax Saver has been down in the third quartile in the last one year. What has gone wrong and how do you plan to improve the performance?
Firstly, I would say that this fund has a slightly longer orientation, which is reflected in the portfolio turnover ratio. Secondly, it is the last few months of volatility and underperformance feeding into the one-year performance, and that's why the performance looks a bit subdued. But in terms of our fundamental construct, nothing has changed. It just so happened that some of our big winners of last year have remained subdued or corrected in the last few months, and as a result, the near-term performance looks a bit down.
For example, if we look at the Power sector, where we have meaningful exposure, some of these power stocks have corrected very meaningfully in the last few months, which has been a drag on our performance. If I discuss misses, we were underweight in the IT sector, but IT stocks, despite being expensive, have continued to do well, particularly on the mid-cap side. At that time, given the likely growth challenges, our view was that valuations were a bit higher. Today, we continue to have a positive view of the Power sector and some other recently corrected winners, and we continue to hold on to them. Therefore, our approach remains consistent. The approach continues to evaluate every opportunity on relative risk-reward available in the market. We are confident it's just a passing phase, and the fund will return to where it was a few months ago.
After the recent correction, which sectors or themes look attractive, and which still seem overpriced?
If you look at our portfolios and I have to put that in three broad sectors, Consumer Discretionary, Power sector-related exposures, Banks in general, or the Financials, they are the ones that continue to look good to us now. If we look at Consumer Discretionary, I think there are very clear structural tailwinds for the consumer sector in India. We cannot ignore that India is a young country with growing per capita income, which would lead to improving penetration and trends on premiumisation playing out over long periods. There are multiple categories to consider when investing. If you look at our fund, we have exposure to retail and QSR (quick service restaurant) and have a well-diversified portfolio across multiple profit pools in the consumer space.
In the Power sector, our view is that the demand-supply equation remains favourable. If you look at the last few years, there have been no significant additions to conventional supply, but the demand has continued to grow. So, this is something that is positive for existing asset owners. At the same time, tremendous opportunities are coming up due to the changing energy mix. With India committing to putting 500 gigawatts of renewable energy capacity by 2030, I think this change in the energy mix, which is coming our way, will create opportunities for the entire ecosystem.
The third sector I discussed is Banking and Financial Services; their valuation remains favourable within the overall market context. At the same time, most of the headwinds we were worried about are abating. So, in that sense, I think these three sectors are where we are comfortable and have significant overweight exposures.
Concerning underweights, I am referring to global sectors, where growth can become challenging due to ongoing uncertainty. That is where we would be cautious, and we would remain underweight.
Also read: Why's Tata's small-cap fund excelling? Fund manager explains
Ask Value Research 

 New episodes every Friday







 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


